
B2B cross-border payments will move roughly $173 trillion in 2026. Stablecoin payments will account for about $390bn of that — under 0.5% of wholesale cross-border value, up from $3bn in 2022. Both numbers matter, and most coverage picks one and ignores the other.
What the acquisitions say is more precise than either figure. Windsor Drake’s Q2 2026 benchmark puts the cross-border cohort at 6.5x EV/revenue overall, but splits sharply by rail: stablecoin and on-chain settlement at 10–15x, B2B FX and multi-currency platforms at 7–12x, embedded cross-border specialists at 6–9x, modern digital remitters at 2–4x, and legacy money-transfer operators at 0.8–1.2x. A buyer paying ten times revenue for a rail carrying half a percent of the volume is not buying today’s flow. The seven deals below show what they think they are buying, and in five of them the priced asset was a regulatory permission attached to the rail.
1. Circle acquires Tazapay for $400m — the stablecoin issuer buys the bank rails
Announced 8 September 2026, expected to close in 2026. Tazapay is a Singapore B2B cross-border platform processing over $25bn in annual volume, of which roughly 60% already involves stablecoins, with local payout networks across Asia-Pacific and relationships with more than 60 banks and fintechs. Circle issues USDC; it did not buy a blockchain. It bought correspondent relationships and local payout coverage — the part of the journey where a stablecoin still has to become local currency in a local account. Singapore’s regulatory perimeter is doing quiet work in this deal: the payout network is only as usable as the licences underneath it.
2. Mastercard acquires BVNK for up to $1.8bn — the network buys the bridge
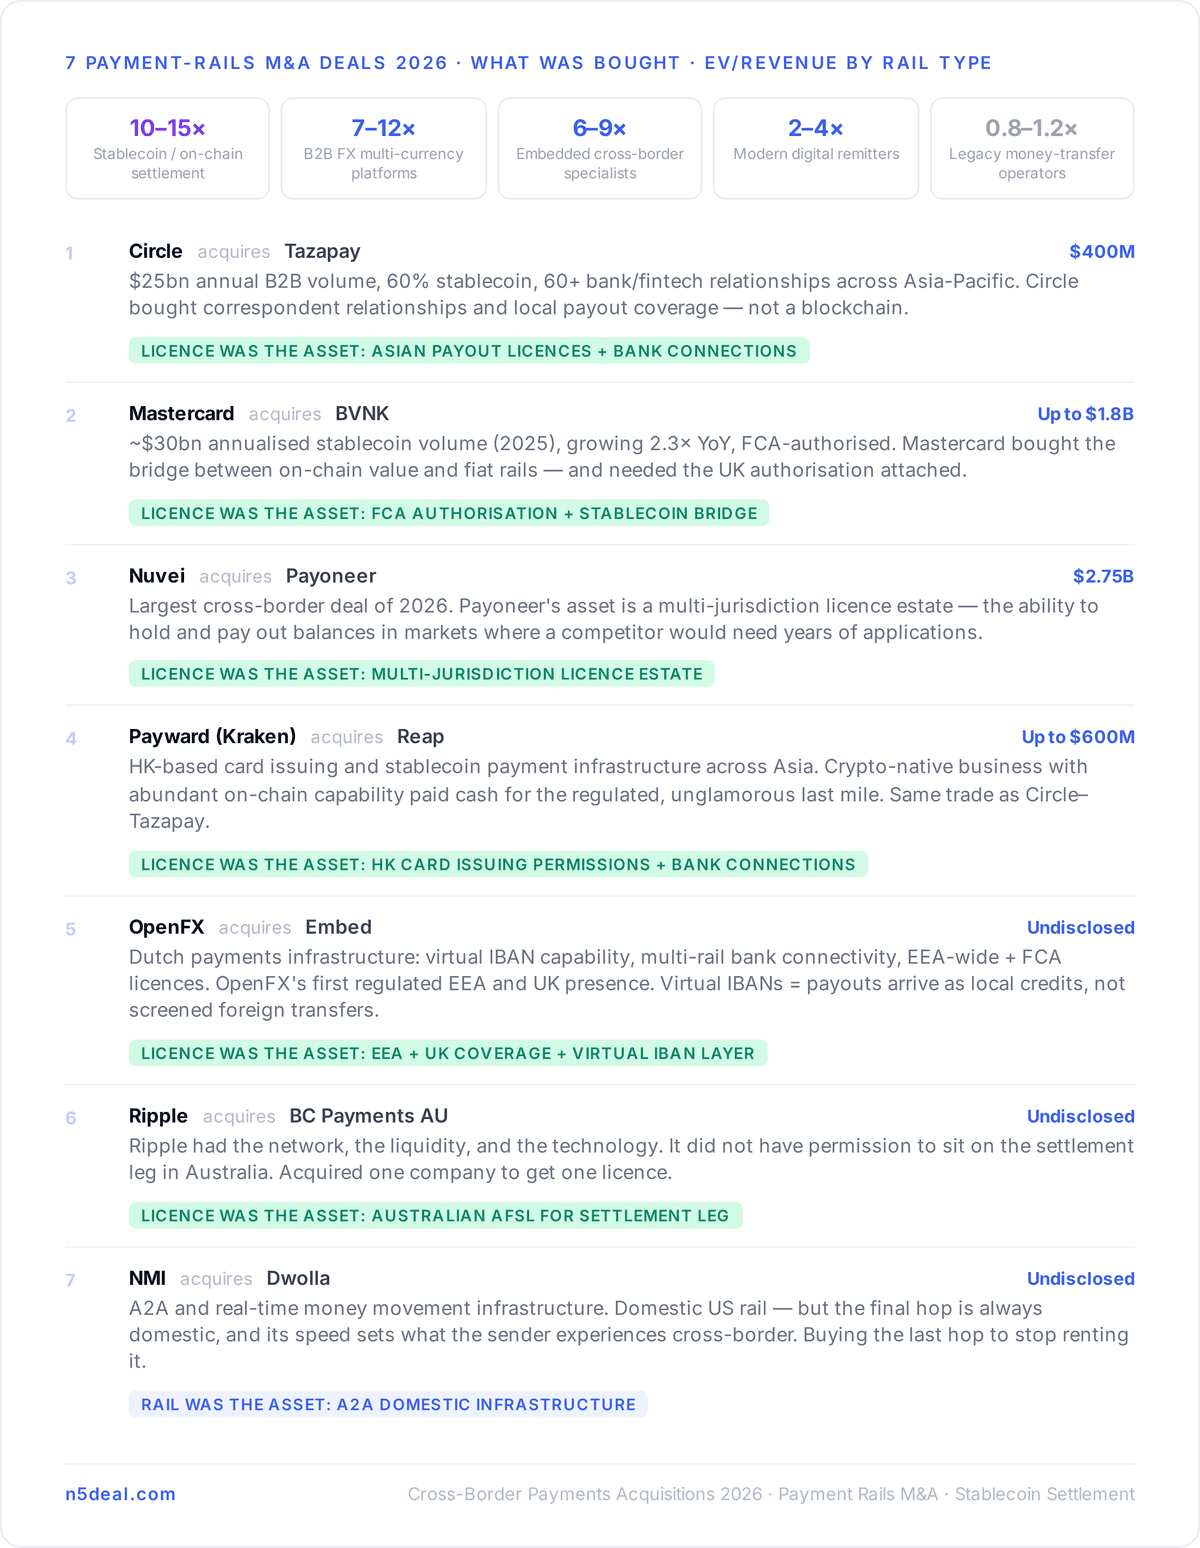
Announced 17 March 2026, closed 3 August 2026, with $300m contingent on performance. BVNK was running roughly $30bn annualised stablecoin volume in 2025, growing 2.3x year on year, and is FCA-authorised. Mastercard described the approach as chain-agnostic, avoiding ecosystem lock-in. The structural point: the world’s second-largest card network concluded that connecting on-chain value to fiat rails was a capability to acquire, not to build, and that the acquisition had to come with a UK authorisation attached rather than a technology stack alone.
3. Nuvei acquires Payoneer for $2.75bn — the largest licensed network taken off the public market
Announced June 2026, and the biggest cross-border transaction of the year by value. Nuvei, itself privately held, bought a Nasdaq-listed cross-border payments business to fold its banking network and licence estate into a single acceptance platform. Payoneer’s asset is not a rail in the technical sense — it is a multi-jurisdiction licence estate that lets one entity hold and pay out balances in markets where a competitor would need years of applications. That estate is what $2.75bn bought.
4. Payward acquires Reap for up to $600m — an exchange buys the Asian last mile
Announced 7 May 2026, completed 1 July. Kraken’s parent bought Hong Kong-based Reap for card issuing and stablecoin payment infrastructure across Asia. Read alongside Circle–Tazapay, this is the same trade twice in one year: a crypto-native business with abundant on-chain capability paying cash for the regulated, unglamorous last mile. The rail that was scarce turned out to be the bank connection, not the blockchain — which is also why a crypto licence and a payment licence are not interchangeable for this kind of product.
5. OpenFX acquires Embed — buying a virtual IBAN layer and an EEA footprint
Announced 2 June 2026, value undisclosed, closing expected in Q3 2026 subject to regulatory approval. Embed is a Dutch payments infrastructure business bringing virtual IBAN capability, multi-rail bank connectivity, and licences across all EEA states plus the UK through the FCA. OpenFX stated the obvious consequence: this is its first regulated presence in the EEA and the UK. Virtual IBANs are the least discussed piece of cross-border modernisation and among the most decisive — without them a payout looks foreign to the receiving bank, and foreign payouts are what get held, screened and returned.
6. Ripple acquires BC Payments Australia — control of the settlement leg
Announced March 2026, value undisclosed. Ripple bought the company to obtain an Australian Financial Services Licence, stating the purpose as overseeing settlement and optimising transaction routing on its payments platform. This is the smallest deal on the list and one of the more instructive: the buyer already had the network, the liquidity and the technology. What it did not have was the permission to sit on the settlement leg itself in that market, and it bought a company to get it.
7. NMI acquires Dwolla — the domestic rail that decides the cross-border experience
Announced 19 May 2026, value undisclosed. NMI folded Dwolla’s account-to-account and real-time money movement infrastructure into its embedded payments platform. A2A is a domestic US rail, so it looks out of place on a cross-border list until you follow a payment to its end: the final hop is always domestic, and its speed and cost set what the sender actually experiences. Buying the last hop is how embedded platforms stop renting it — the same logic that runs through the twelve capabilities behind a banking-as-a-service stack.
What the seven deals have in common
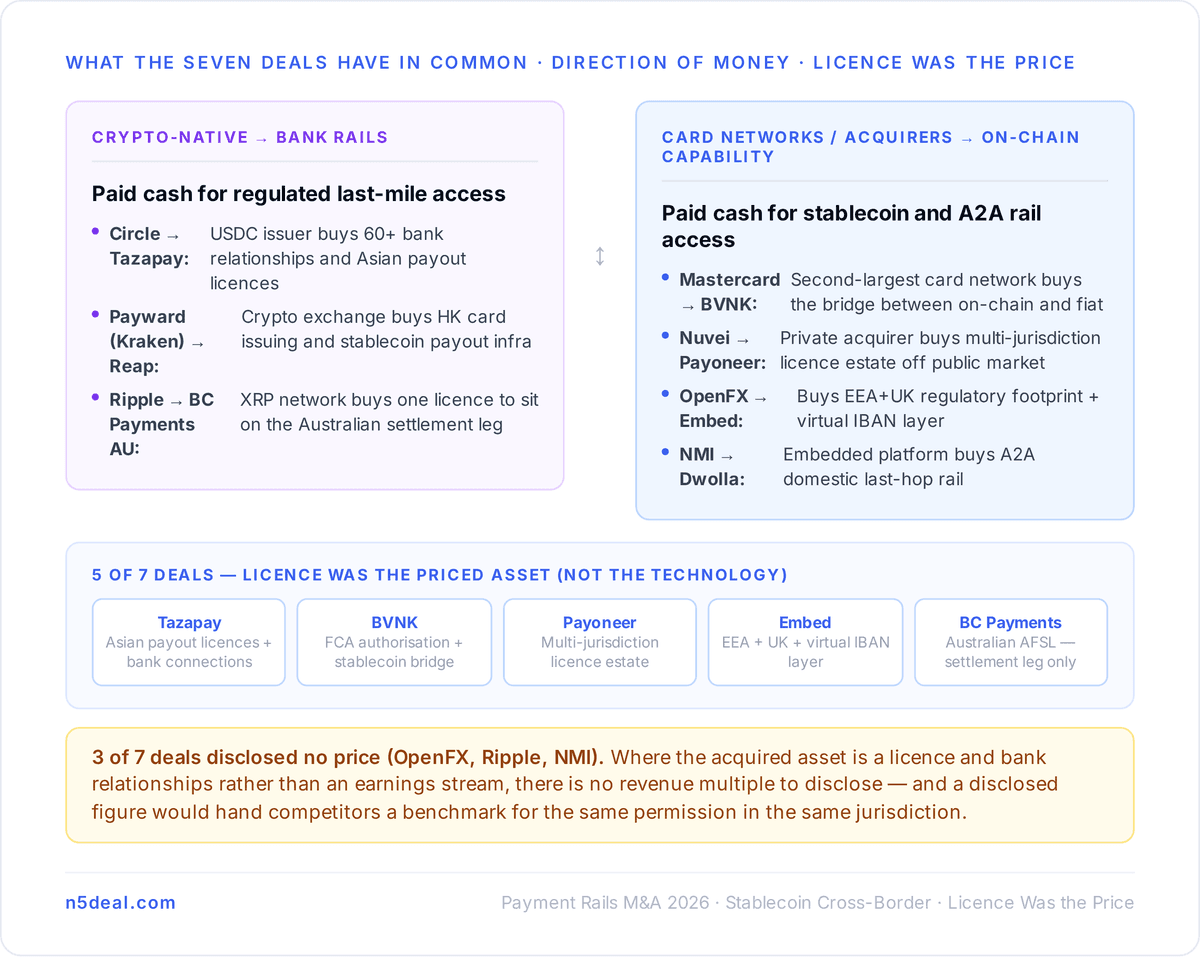
Five of the seven were bought at least partly for authorisation the acquirer did not hold: Tazapay’s Asian payout licences, BVNK’s FCA permission, Payoneer’s licence estate, Embed’s EEA and UK coverage, and BC Payments’ AFSL. Three disclosed no price at all. The direction of the money is worth stating plainly — crypto-native firms spent cash on bank rails and regulated entities, while card networks and acquirers spent cash on on-chain capability, and both sides paid a premium over the 0.8–1.2x that a legacy money-transfer operator commands. If you hold a licensed payments entity in a corridor these buyers care about, the current listings show where comparable assets are priced today.
Comments
Frequently Asked Questions
Clear, concise info to help you understand the process!